How to Improve Your CIBIL Score
Your CIBIL score can impact everything from loan approvals to interest rates, but improving it is absolutely possible with the right strategy. This guide breaks down how CIBIL scores work, the biggest factors affecting your credit health, and practical steps to rebuild your score faster. Whether you're recovering from missed payments, high credit utilization, or a loan settlement, learn realistic timelines and actionable ways to move toward a stronger financial profile.

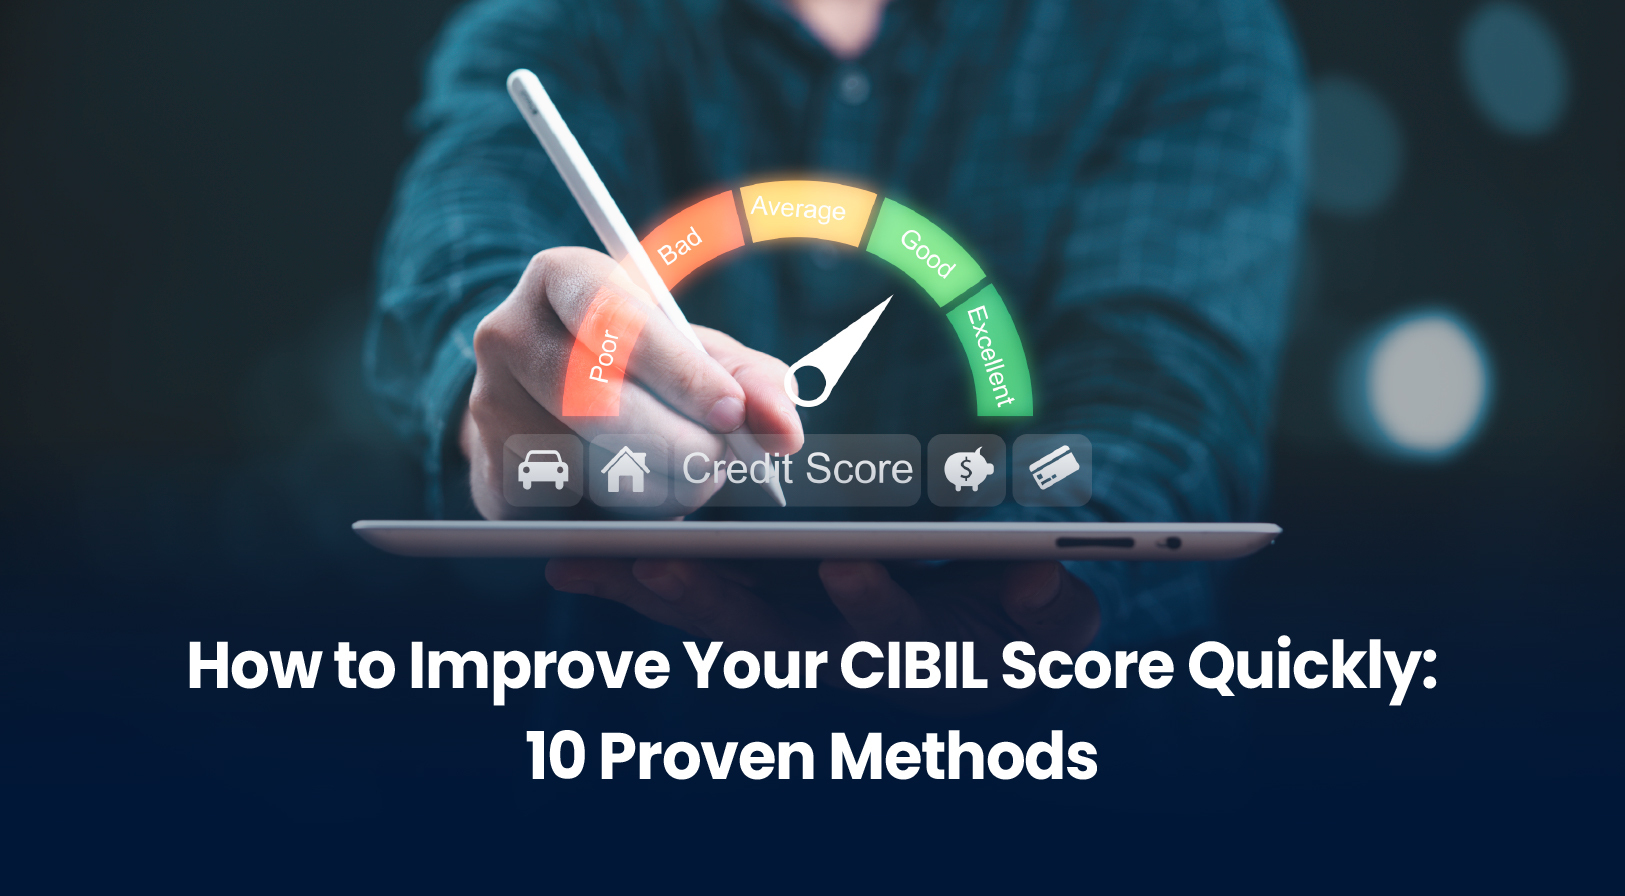
CIBIL score is your three-digit number ranging from 300 to 900 and measuring your credit repayment behaviour. Lenders prefer a score above 750 to offer you the best loan terms. However, there are clear steps you can take to improve your score in case it is below 750, but there is no quick fix to your credit score.
This article explains what influences your CIBIL Score, how to deal with each of these factors, in what time frame changes happen and what to do if your score was hurt by a settlement.
Factors affecting your CIBIL score
CIBIL's scoring methodology is proprietary and not disclosed. However, approximate factor weightings reported by different financial services providers are known and consistent with the way credit scoring normally works:
Payment history (approx. 35% weighting), whether you make timely payments on your EMIs and credit card bills. This factor has the biggest weight. Any EMI payment delayed for 30 days or more is noted in your report as "Days Past Due" (DPD) and lowers your score.
Credit utilisation (approx. 30% weighting), percentage of your total credit limit which you use. For example, if your credit card limit is ₹1,00,000 and your balance is ₹80,000, your utilisation is 80%. Utilisation above 30% is considered high and lowers your score.
Age of credit history (approx. 15-25% weighting), the age of your accounts. Long-term history with consistent repayment demonstrates financial stability. Closing your oldest credit card account may lower your score.
Credit mix and other factors (approx. 10-20% weighting), having both secured (home and auto loan) and unsecured (credit card and personal loan) credit. Also includes hard inquiries in the last period (applications for loan or credit card).
Note: Percentages are approximate and based on secondary sources (BankBazaar, Fibe, Bajaj Housing Finance). Official numbers are not provided by TransUnion CIBIL.
The fastest way to change your score: correct mistakes on your report
The very first step is to obtain your credit report and review it for any mistakes. Such mistakes are not uncommon, incorrect loan balances, payments marked as overdue but made in time, accounts that belong to another person.
Correcting mistakes is the fastest way to influence your score, since you remove information that does not belong to your report.
How to check and dispute:
Get your free credit report at cibil.com (you are entitled to one free report per year from TransUnion CIBIL).
Review all accounts in your report, check their payment status, outstanding balances and whether all accounts belong to you.
If you find any mistake, dispute the report through CIBIL's online dispute resolution system at cibil.com. CIBIL contacts the lender, and the lender has 30 days to reply. If the lender confirms the mistake, your report will be corrected and your score will be recalculated.
Corrected mistakes will be reflected in your score in 30-45 days.
Read More: How to Check CIBIL Score in Minutes
What you can do to improve your score over time
There is no legitimate way to improve your CIBIL score by a certain number of points in a certain number of days. Anyone who promises "improve your score by 100 points in 30 days" either misleads you or sells something.
However, you can address each of these factors. Your improvement depends on how badly you damaged your profile, how many accounts you have and how diligently you do everything.
Make timely payments on all EMIs and credit card bills
It is the most important habit. Payment history factor is the most influential factor when it comes to your score. Set up auto-debit or standing instructions for all EMIs and at least the minimum due on credit cards. A single missed payment is recorded in your report and stays there for years.
If you have already missed some payments in the past, the damage is done, but each subsequent on-time payment leaves good data in your report and counterbalances your previous mistakes.
Bring your credit card utilisation down to below 30%
If your credit card utilisation is high (70-80% of your credit limit), paying off the balance is one of the most impactful things you can do. Each month, lenders report your balance to CIBIL and as soon as they report the lower balance, the utilisation factor in your score is impacted positively.
The standard recommendation is to keep your utilisation below 30% of your total credit limit. If you have several credit cards, utilisation is calculated for each of them and for all your cards together.
If you are unable to pay off the balance right away, you can contact your card issuer and ask for the increase of your credit limit. If the bank agrees (without performing hard inquiry, if possible), your utilisation ratio will drop, although your balance stays the same. Some banks will not agree and will perform the hard inquiry, ask before proceeding.
Do not close old credit card accounts
Closing your old credit card shortens the age of your credit history and reduces your total credit limit (increasing utilisation ratio). You should keep old cards open unless they have an annual fee which you are unable to justify. Use them once in a while for small purchases.
Do not apply for credit in rapid succession
Each time you apply for a loan or credit card, the lender pulls your credit report, hard inquiry. Hard inquiries performed in a short time period indicate to the model that you desperately need credit. Therefore, space out applications for credit products at least several months.
Checking your own score is a soft inquiry and has no effect on your score.
Maintain a balance of both secured and unsecured credit accounts
Having both secured (home or auto loan) and unsecured (credit card or personal loan) credit is considered positively by the score model. However, you should not rush, you should not take unnecessary loans just to balance your credit mix. If you already have a balance of these accounts, maintain them current.
Realistic time frames
CIBIL scores are usually recalculated whenever lenders report data, which happens once per month in a cycle. Whatever you do right now, its effect on your score will become visible after the lender will report the updated information.
As an approximation, based on how factors work:
Decrease credit card utilisation from 80% to 30% will show effect within 1-2 billing cycles (30-60 days), since the lower balance will be reported to CIBIL.
Correction of an error on your report will have an effect within 30-45 days after the dispute is accepted by CIBIL.
Timely payments will start showing effect slower, 3-6 months of uninterrupted payment history start indicating good behavior. Clean payment history for one year is a better signal both for the score model and for lenders checking your report.
The effect of missed payments fades with time but does not go away quickly. Older negative data carries less weight than recent one, however, payment history on the report is visible for quite a while.
TransUnion CIBIL does not provide the point weightings of each action. Its effect depends on your overall profile. A person with a thin credit history (just one credit card, no loans) will be more affected by any change than a person with a long credit history.
Improving your score after a loan settlement
Loan settlement, when you repay a partial amount and the lender accepts it as full repayment of the debt, is marked as "Settled" in your report. It is different from "Closed" (meaning you paid in full) and has a negative impact on your score and on lenders' assessment of your application.
A settled loan stays on your report. Its retention period depends on CIBIL's data retention policy. You can change settlement status to "Closed" if you pay the rest of the outstanding balance to the lender. This will be worth doing if you can afford it, since "Closed" status looks much better than "Settled" status for both the score model and for the lender checking your application.
Steps after a settlement:
If you are able to pay the remaining amount to the lender and change the status of your account to "Closed," obtain a No Dues Certificate or a letter proving that change of status.
Make sure the lender reports your updated status to CIBIL. Follow up, sometimes lenders report the information slowly.
Focus on all your currently active accounts. Timely payments on active accounts demonstrate your improved behavior to the lender most clearly.
Do not apply for credit immediately after the settlement. A clean payment history for several months will be better proof than several loan applications.
There is no set timeline to recover after a settlement. Your situation depends on how many accounts you have, how they are and how consistent you are in demonstrating improved behavior. A lender checking your application will see your settlement in your report and form an opinion. An old settlement with a clean recent track record looks better than the opposite.
What does not work
Services charging fees for "fixing" your CIBIL score. No third-party company can change your credit data. Only the lender who supplied the data can change it (either by correcting an error or changing the status). If the information on your report is correct, no one can remove it.
Opening a lot of new accounts to build history. It will backfire, hard inquiries performed in a short period reduce your score, while new accounts have no payment history (decreasing average account age).
Paying just the minimum due on your credit card. It prevents you from defaulting (which is good), but your outstanding balance remains high and raises your utilisation ratio. Pay as much above the minimum due as you can.
Being a guarantor to "build credit." Being a guarantor does not build your credit history. However, if the primary borrower defaults, default will be recorded in your report.
About the Author
Divya Kumari
SEO Strategist & Finance WriterDivya Kumari is an SEO and Content Strategist with experience in organic traffic growth, topical authority building, and content-led SEO strategies. She specializes in creating user-focused content for finance and SaaS websites, helping brands improve visibility through structured content planning, internal linking, and search optimization techniques.
Borrow. Protect. Grow.
All in one app.
- Compare loan offers
- Buy insurance in minutes
- Invest in mutual funds
- Check credit score free
- Track all your applications
Explore More Articles
What to Do When Your Travel Budget Falls Short

How to Finance Your Dream Vacation Responsibly
On this page
About the Author
Divya Kumari
SEO Strategist & Finance WriterDivya Kumari is an SEO and Content Strategist with experience in organic traffic growth, topical authority building, and content-led SEO strategies. She specializes in creating user-focused content for finance and SaaS websites, helping brands improve visibility through structured content planning, internal linking, and search optimization techniques.
Borrow. Protect. Grow.
All in one app.
- Compare loan offers
- Buy insurance in minutes
- Invest in mutual funds
- Check credit score free
- Track all your applications