Managing Festival Expenses: Personal Loan Guide
Festivals often bring additional expenses for shopping, gifts, travel, decorations, and celebrations. This guide explains how to plan and manage festival expenses, create a realistic budget, avoid unnecessary debt, and explore personal loan options when extra funds are needed for festive occasions.

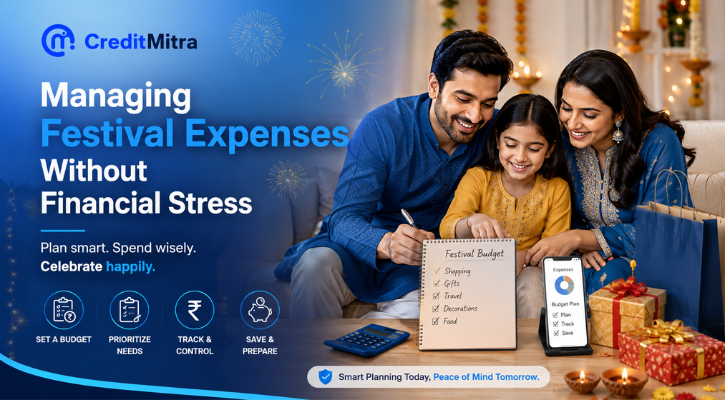
It is only four weeks away until Diwali. You have started making lists of purchases that you need to make for the festival. They include gifts for family members, buying new clothes for the kids, decorating your home, buying sweets boxes for neighbours, purchasing electronics you have wanted for a long time, etc. You also wish to go on vacation with your family as your spouse has been asking for it for the past two years now. Let's do some math here. ₹80,000, maybe even ₹1,00,000 is what you think. Your savings amount? Only ₹35,000 was kept as an emergency. This is how festival expenses hit Indian households every year and they all handle this problem in a terrible manner. Mostly they either use up their savings, borrow with credit cards (which comes with hefty interest rates 36-42%) or simply feel bad about spending less than last year. According to a Deloitte study, Indian households tend to spend 25%–40% extra during festive seasons compared to other times of the year. This is not overspending. This is real spending and it is also a significant cultural practice in India. Indian festivals include: Diwali: gifts, sweets, clothes, house decoration, electronic items, jewellery, lighting Eid: new clothes, feasting, gift giving (Eidi), home decoration, gathering of family Christmas: gifts, travel, parties, decoration, special meals Onam: special feasting (sadhya), new clothes, family travel and celebration Wedding season (Oct-Feb): urban Indian weddings can easily cost between ₹15 lakh to ₹50 lakh, whereas, wedding season which includes Diwali and Eid adds to the cost because of the high demand for the places and providers, the weddings held during Diwali and Eid cost 20-30% extra. As per industry estimates, there is a 30-40% increase in consumer spending during major festivals like Diwali, Eid, and Christmas. So the question is not whether you should spend or not, but the question is how to fund this money in an efficient manner, so that you don't have to suffer financially for the new year. Knowing how much people spend in average will help you benchmark your festival expenses and plan accordingly: Average Budget for Diwali: Average Budget for Eid: Wedding during festival season: A budget for a typical middle-class wedding in India is between ₹5 lakh to ₹10 lakh. During Diwali or Eid season weddings, costs become 20-30% more. Add a buffer of 10-20% for price rise, last-minute travel arrangements and unanticipated expenses. Most households tend to underestimate exactly this amount. Read More: Minimum CIBIL Score for Personal Loan Approval Spending money out of your own savings is free. There is no interest or EMI involved. Problem: Most Indians don't have enough savings for festival expenses without touching their emergency fund. Using up your emergency buffer for the purpose of celebrations leaves you unprotected from any genuine financial emergencies like a medical emergency, job loss, car accident, etc after Diwali. Use savings for: Predictable, recurring and small festival expenses (₹10,000-₹30,000 range) Very convenient method but can be dangerous if the entire balance isn't cleared. Credit card interest: 30-42% p.a. For larger festive expenses like purchasing appliances or renovation of your home, a personal loan can be a good alternative for Diwali and wedding season. Example: ₹50,000 of festival shopping using credit card, paying minimum (₹2,500/month): Total repayment time: 32 months Total interest paid: ₹29,000+ Total cost of festival shopping: ₹79,000 Use credit card for: Small expenses (under ₹10,000) which you are able to clear off completely within 45 day grace period A personal loan for a wedding or festival expenses is unsecured loan type, requires very limited documentation and disbursed instantly. Interest rates on a marriage loan begin from 9.99%. Personal loan interest: 10.5%-18% p.a. The same ₹50,000 needed for festive expenses, using personal loan at 14%, 12 months repayment period: Monthly EMI: ₹4,481 Total interest paid: ₹3,772 Total cost of festival shopping: ₹53,772 Difference between savings and credit card: ₹25,228 cheaper Personal Loan for Festival Expenses is typically in the range of ₹15,000 to ₹3,00,000 with the most common repayment tenure being 6-24 months. Make an actual list rather than trying to estimate in your mind. Gifts (to family, friends, colleagues) Clothes (for each family member) Sweets and dry fruits Home decoration and lighting Electronic devices you had planned to purchase Vacation Restaurant meals, parties Wedding contribution (if any) Puja expenses and services Essential: These are the things that you will certainly be spending on regardless (basic gifts, clothes, traditional puja) Non-Essential: Nice to have additions (new furniture, upgrade to electronics, holiday travel). This distinction becomes important when it comes to financing decision making. Add a buffer of 10-20% for price rises, last-minute travel arrangement and unanticipated purchases. If your estimate is ₹60,000 then you need to plan for ₹69,000. Prices of goods tend to rise during festival times. Last-minute expenses happen. Your budget tends to always expand. Total available savings (without using your emergency fund) - Total festive budget = Funding gap Example: Total budget: ₹75,000 Available savings (while maintaining ₹25,000 as emergency fund): ₹30,000 Funding gap: ₹45,000 This is the gap which will be filled by a personal loan. Before borrowing, you need to make sure that your EMI is affordable for you: Monthly income: ₹50,000 Existing EMIs: ₹10,000 Available for additional EMI: ₹15,000 (30% of remaining income) ₹45,000 personal loan at 14% for 12 months = EMI of ₹4,033. This is well within your comfort level. You should consider personal loan if: Funding gap is ₹20,000+ (anything lower can be managed by savings or credit card) You prefer having fixed EMI (as against variable revolving credit card debt) You can afford to pay off in 6-24 months comfortably You have CIBIL 650+ for good interest rates You don't want to use your savings for emergency fund Avoid personal loan if: Funding gap is low (under ₹15,000), then use savings or repay credit card amount quickly Your existing EMIs already exceed 40% of income CIBIL score is below 600 (interest rates will be extremely high) Uncertain about stability of your income in coming 12 months Monthly EMI for a ₹1,57,500 personal loan at 17% interest rate for 15 months is approximately ₹11,729 per month. Total interest payment: ₹18,435. Typical festival loan scenarios (interest rate 14% p.a.): CreditMitra offers instant personal loans up to ₹5 lakh , fully digital, limited documentation, disbursal in minutes. Before taking a loan, you should try reducing the gap first: 1. Start early shopping (August-Sep) Prices for festive goods rise sharply in October and November. Same products cost 15-25% less 2 months prior to the festivities. 2. Set a gift limit in your family Many families secretly desire lower gift budgets. Make an official suggestion of a "max ₹500 gift" policy. Saves thousands for everyone. 3. Buy electronics on no-cost EMI (if it is really true) Be careful about processing fees. If it really has zero EMI then utilize it. Real zero EMI is a great saving opportunity. 4. Plan vacation ahead of time Festival travel prices surge 2-3X if booked last minute. Booking 6-8 weeks prior is always a good idea. 5. Do your own home decoration YouTube is full of excellent Diwali/festival decoration tips. Cost: ₹500 in material vs ₹3,000 for ready-made decoration kits. 6. Gift pool in your family You can pool gifts for your parents with your siblings. Great gift and cheaper individually. 7. Experience instead of gifts A family dinner (₹3,000) will give you more pleasant memories than a similar value gift. The October to February period is both the festive season and wedding season in India. Typically a middle-class family in Delhi will plan a wedding of 400 guests with a budget of ₹25 lakh, but usually spends around ₹32 lakh due to seasonal surcharges. If you find yourself in this position: Separate budgets for the festival and wedding are different buckets Plan wedding loan separately, since this is larger amount of money and tenure 24-60 months Festival expenses loan separately since this is smaller amount of money and tenure 6-12 months Apply for both from one platform , one single application, multiple products A personal loan can be taken separately to finance this gap without liquidating your savings. CreditMitra provides instant personal loans up to ₹5 lakh , specifically designed for such needs: Festival loan via CreditMitra: 100% digital, no branch visits, no paper forms Instant approval, disbursal within minutes of approval Up to ₹5 lakh, covering all festive expenses including wedding contribution Flexible tenure, 6 to 60 months according to your repayment ability Transparent pricing, knowing your rate and EMI before confirmation No collateral, just based on your income and CIBIL score Festival loan process via CreditMitra: Apply online on creditmitra.in in 5 min Submit KYC (Aadhaar + PAN) digitally Income proof submission (bank statement or salary slip) Instant approval of your loan Funds in your account in minutes after approval Q: Is it wise to take a loan for festival expenses? Q: How fast can I get a festival loan? Q: Will my CIBIL score suffer from a festival loan? Q: How much festival loan can I get? Q: Should I use savings or borrow money for my festive expenses? Q: Am I able to prepay my festival loan in case of getting a bonus? Festivals are supposed to be enjoyable events not financial nightmares lingering in the new year. The smart strategy in 2026 is as follows: Budget first list everything, add 15% buffer Use savings whatever amount you can afford safely (without using your emergency fund) Reduce gap early shopping, gift limit, DIY when possible Take personal loan for the remaining gap (not the credit card at 36-42%) Keep EMI comfortable under 30% of your income Replicate with discipline timely payments improve your CIBIL score ₹50,000 personal loan for your festival at 14% interest rate costs ₹3,772 in interest over 12 months. It is the cost of enjoying it with your family without any financial worries, and without using your savings which you may urgently need in January. Apply for CreditMitra's instant personal loan now. Up to ₹5 lakh, 100% digital, approval in minutes. Celebrate without compromise, repay without troubles.The Reality Behind Indian Festival Expenses
Indian Festival Expenses: How Much Do People Spend?
3 Options for Financing Your Festival Expenses (By Cost-effectiveness)
Option 1: Savings (Best but Limited)
Option 2: Credit Card (Most Costly Option)
Option 3: Personal Loan (Smartest Choice for Large Amounts)
Creating Your Festival Budget (Step By Step)
Step 1: Write Down All Expected Expenses
Step 2: Classify Expenses As Essential vs Non-Essential
Step 3: Add the 15% Buffer
Step 4: Calculate the Funding Gap
Step 5: Estimate EMI Comfort
Personal Loan for Festival Expenses: Is It Suitable for You?
Festival Loan: Real Life EMI Examples
7 Tips to Save on Festival Expenses
Double Expense Problem When Festival Season & Wedding Season Intersects
How CreditMitra Makes Festival Borrowing Easy
FAQ: Festival Expenses and Personal Loans
A: Yes, when done in a smart way. Taking a personal loan at 10.5-14% interest rate for financing your festival expenses is a far smarter choice than spending through credit card at 36-42%. The key is to borrow only the necessary amount and pay it back with a comfortable EMI.
A: CreditMitra disburses money within minutes after approval. It is recommended to apply at least 1 week before your festival starts.
A: Making an application for the loan may create temporary impact. But paying off your EMI on time may actually improve your CIBIL score.
A: CreditMitra offers up to ₹5 lakh. Actual loan amount is based on your income, CIBIL score and EMIs.
A: You should use savings for routine smaller expenses. Borrowing is recommended in case your festival gap is ₹20,000-25,000 and depleting your savings will leave you without any emergency fund.
A: Yes. Most of the personal loans (including CreditMitra's) allow prepayment.Conclusion: Celebrate Without Any Worries, Borrow Wisely
About the Author
Divya
SEO Strategist & Finance WriterDivya Kumari is an SEO and Content Strategist with experience in organic traffic growth, topical authority building, and content-led SEO strategies. She specializes in creating user-focused content for finance and SaaS websites, helping brands improve visibility through structured content planning, internal linking, and search optimization techniques.
Borrow. Protect. Grow.
All in one app.
- Compare loan offers
- Buy insurance in minutes
- Invest in mutual funds
- Check credit score free
- Track all your applications
Explore More Articles
What to Do When Your Travel Budget Falls Short

How to Finance Your Dream Vacation Responsibly
On this page
- The Reality Behind Indian Festival Expenses
- Indian Festival Expenses: How Much Do People Spend?
- 3 Options for Financing Your Festival Expenses (By Cost-effectiveness)
- Creating Your Festival Budget (Step By Step)
- Personal Loan for Festival Expenses: Is It Suitable for You?
- Festival Loan: Real Life EMI Examples
- 7 Tips to Save on Festival Expenses
- Double Expense Problem When Festival Season & Wedding Season Intersects
- How CreditMitra Makes Festival Borrowing Easy
- FAQ: Festival Expenses and Personal Loans
- Conclusion: Celebrate Without Any Worries, Borrow Wisely
About the Author
Divya
SEO Strategist & Finance WriterDivya Kumari is an SEO and Content Strategist with experience in organic traffic growth, topical authority building, and content-led SEO strategies. She specializes in creating user-focused content for finance and SaaS websites, helping brands improve visibility through structured content planning, internal linking, and search optimization techniques.
Borrow. Protect. Grow.
All in one app.
- Compare loan offers
- Buy insurance in minutes
- Invest in mutual funds
- Check credit score free
- Track all your applications